Ankara --:-- · —
bilgi@utuhukuk.com
0536 593 16 00
UTU Hukuk ve Danışmanlık16 min readUpdate:
A mining licence and land ownership are separate concepts under Mining Law No. 3213. Owning an immovable property does not in itself confer the right to explore for or operate the minerals lying beneath it. Minerals are under the sovereignty and disposal of the State; mining activities by private persons are based on the licences and permits regulated by law. For this reason, land ownership, the mining licence, the production permit and the financial obligations must each be assessed separately.
In this article, we explain, within the framework of Mining Law No. 3213, the definition of a mineral, the persons who may hold mining rights, exploration and operating licences, transfer and inheritance transactions, the mining registry and the principal financial obligations. The aim is to set out which right may be exercised, and under which conditions, from the perspective of the licence holder, the investor, the heir and the landowner.
Mining law covers the rules on the exploration and operation of minerals as natural resources, the acquisition of rights over them, and the abandonment of the site when the activity ends. Production, shipment, inspection, environmental obligations, the transfer of the licence and disputes arising from mining rights are also connected with this field. Mining activities are carried out in conjunction with the Mining Law as well as environmental, forestry, occupational health and safety, tax and real property legislation.
According to Article 2 of Mining Law No. 3213, substances that occur naturally in the earth’s crust and in water sources, that have economic and commercial value and that fall outside oil, natural gas, geothermal and water resources are deemed, for the purposes of the Law, to be minerals . The mineral groups and sub-paragraphs in the Law are important in terms of licensing and financial obligations. [1]
Turkish Petroleum Law No. 6491 contains separate rules for oil and natural gas, and Law No. 5686 for geothermal resources and natural mineral waters. Nevertheless, it cannot be said that all water resources are subject to Law No. 5686. For example, Law No. 167 on Groundwater is also taken into account with respect to groundwater. The applicable licensing regime should not be chosen before the legal nature of the resource has been determined. [4]
Article 168 of the Constitution provides that natural wealth and resources are under the sovereignty and disposal of the State and that the right to explore for and operate them belongs to the State. The State may grant this right to natural or legal persons for a specified period under the conditions laid down by law. Article 4 of the Mining Law also expressly states that minerals are not subject to the ownership of the land in which they are located. [1, 3]
Article 718 of the Turkish Civil Code links the scope of land ownership to the airspace above and the subsoil below to the extent that their use is beneficial. The same article states that this scope is subject to legal restrictions. In respect of minerals, the special restriction derives from Article 4 of the Mining Law. Therefore, an ore deposit beneath an immovable property does not become an asset that the landowner may freely dispose of merely by virtue of land ownership. [1, 3]
Land ownership
Turkish Civil Code, Art. 718: the airspace above and the subsoil below to the extent that their use is beneficial; subject to legal restrictions.
Mining right
Constitution, Art. 168 and Mining Law, Art. 4: minerals are under the sovereignty and disposal of the State and are not subject to the ownership of the land.
Nor can it be said that the licence holder is a co-owner, together with the State, of the underground mineral. The licence holder’s authority is based on the exploration and operating rights recognised by law. Payment of the state royalty does not create co-ownership or a partnership between the licence holder and the State. Disposal over extracted ore must be distinguished from the legal regime governing minerals not yet extracted.
On the other hand, a mining licence does not confer the authority to use land belonging to third parties free of charge and without limit. Depending on the type of activity and the status of the site, means such as obtaining the owner’s consent, an agreement, the establishment of an easement or usufruct, or, where the statutory conditions are met, expropriation may come into play. The rights of the landowner are assessed under Articles 7 and 46 of the Mining Law and the relevant special provisions. [1]
Priority of the landowner
It cannot be accepted that the landowner is granted, for all mineral groups, a priority to obtain a licence without a tender or a general exemption from the licence fee. Such a right may be asserted only where there is a clear legislative basis in respect of the specific mineral group and transaction.
Under Article 6 of the Mining Law, mining rights may be granted to citizens of the Republic of Türkiye who have the capacity to exercise civil rights, to companies with legal personality established under Turkish law, and to the authorised public institutions and organisations specified in the article. Rights are issued in the name of a single natural or legal person. [1]
Accordingly, for a natural person, citizenship and capacity to act, and for a company, the incorporation, legal personality and representation documents are checked together. A foreign natural person directly holding a licence is not the same as an application by a foreign-capital company established under Turkish law. The legal status of the applicant and any special restrictions are assessed separately.
We have explained the concept of capacity to act in our article on legal capacity and capacity to act under the law of persons .
Prohibition on public officials
Civil servants, other public officials and the General Directorate personnel specified in the Law may not obtain an exploration or operating licence. Those who become civil servants while holding exploration or operating rights must transfer their rights within six months of entering public service. Where a public official acquires a licence by inheritance, the prohibition and the devolution provisions are applied together. [1]
Having the capacity to hold mining rights does not mean that all the conditions required in a licence application have been met. Financial adequacy, project, technical documentation, fee and security requirements may additionally arise at the relevant stage. The scope of these conditions is determined according to the type of application and the mineral group.
An exploration licence allows exploration activities to be carried out in a specific site and in respect of the mineral group covered by the licence. An operating licence, on the other hand, is the legal basis of the right to operate. On moving to production, the operating permit and other necessary permits are of separate importance. The fact that a licence has been granted does not mean that all environmental and land permits have also been granted. [1, 2]
Exploration licence, operating licence and operating permit
| Transaction | Authority conferred |
|---|---|
| Exploration licence | Exploration activities in a specific site and in respect of the mineral group covered by the licence |
| Operating licence | Legal basis of the right to operate |
| Operating permit | Moving to production; other necessary permits are required separately |
During the exploration period, geological studies, sampling, drilling, and well or gallery works may be carried out. The special provisions on minerals or samples necessarily extracted during exploration cannot be interpreted as unlimited authority for commercial production. The coordinate boundaries of the licence, the mineral group and the scope of permitted activity must be observed at every stage.
2025 amendment
The 2025 amendment revised the exploration periods and the security regime in Article 17. Exploration activity reports must be submitted on time and the minimum activities must be carried out. Where no operable reserve is found, exploration licence fees and the tender price may be refunded, subject to the reporting and application conditions in the Law. [5]
The relationship between application and tender also varies according to the mineral group. A first application does not confer a definitive licence right for every site. The scope of the tender, the status of the site and the transitional provisions must be examined. Transactions should therefore be followed not only by reference to the application date, but on the basis of the Law in force and current administrative regulations. [1, 2]
Under the principle of indivisibility in Article 5 of the Mining Law, mining rights cannot be divided into shares and made the subject of transactions. For example, holding half of the same licence in the name of one natural person and the other half in the name of another is incompatible with the rule that a licence is granted in the name of a single person. By contrast, the fact that a company holding a licence has more than one shareholder does not in itself make the licence jointly held.
The transfer of a mining licence, the right to develop visible reserves and the discoverer’s right is subject to the conditions in the Law. The nature of the first-application right is not the same as that of a licence transfer. A party selling its priority in respect of an application to another person does not in itself result in a transfer of the licence. [1]
In the transfer of exploration and operating licences, the statutory transfer fee, the approval of the competent authority and the mining registry formalities are important. Article 5 of the Law provides that, before the transfer, a transfer fee equal to twice the licence fee on the date of transfer is to be collected and that the transfer takes effect upon Ministry approval. Special exemptions and the fee and documentation requirements applicable on the date of the transaction must also be checked. [1]
A contract is not enough
Concluding a transfer agreement between the parties is important in terms of the contractual obligations arising from it; however, it does not replace the administrative approval and registry requirements. Before the transfer, the current status of the licence, its debts, permits, registry entries and any ongoing sanctions should be investigated. A licence transfer and a transfer of company shares are also not the same legal transaction.
Mining rights and obligations devolve by inheritance. The purpose of the special rule is to prevent the inherited licence from being divided into shares and to ensure that rights and obligations are maintained as a whole. [1]
If the heirs agree, the licence may be transferred to one of the heirs who meets the statutory conditions or to a third party. If no agreement is reached, the court, upon the application of one of the heirs, decides to allocate the right to the most qualified of the heirs or, where this is not possible, to sell the licence. The assessment of the most qualified person cannot be reduced merely to the size of the inheritance share or to being wealthier than the other heirs.
Article 5 of the Law provides that, where no court action is involved, licences for which the devolution formalities are not completed within six months will be cancelled. Article 80 of the Mining Regulation also sets a six-month application period running from the date of death. This period runs from the date of death; it is not necessary to wait for the six months to expire before applying. The devolution process should be initiated without delay, taking into account the litigation, application and documentation requirements together. [1, 2]
Death of a company shareholder
The certificate of inheritance, the documents evidencing the agreement, the transferee’s capacity and the registry formalities are dealt with together. The death of a shareholder of a company holding a licence is different: in that case, what is inherited is primarily the company share; if the legal entity holding the licence continues to exist, the provisions on the death of the licence holder do not apply directly.
The mining registry contains technical and financial information in addition to records relating to rights. Under Article 38 of the Mining Law, transfers, devolutions, attachments, pledges, mortgages and terminations are entered in the registry. The registry cannot be regarded merely as a recording system that informs third parties; the Law provides that rights to be acquired over minerals have no effect unless registered. [1]
Therefore, when purchasing a licence, one should not be content with the contract and a photocopy of the licence alone; the current registry entry, the validity status of the licence, any entries preventing transfer and continuing obligations should be examined. The publicity of the registry does not in itself validate an authority that does not actually exist or a transfer contrary to the Law.
In respect of a mining operation, attachment and sale are not treated in the same way as the attachment of an ordinary movable. Article 40 of the Law restricts the imposition of separate attachments or interim injunctions on the wells, quarries, galleries, machinery and other listed elements necessary for the operation. For the sale of the mine as a whole through enforcement, the special procedure in Article 43 and the conditions for the purchaser to obtain a licence are taken into account. [1]
A claim for allocation on grounds of inheritance, a complaint against an enforcement act, an action arising from a contract and the annulment of an administrative licensing act are different disputes. No general rule can be laid down that all of them are to be resolved by the civil court of peace. The competent forum and interim legal protection are determined according to the nature of the specific claim. A stay of execution in a dispute arising from an administrative act should not be confused with an interim injunction in a private law dispute.
The principles on the protection of the persons concerned in the withdrawal of administrative acts acquired rights in administrative law in our article.
The licence holder’s financial obligations have different legal bases; the principal ones can be summarised as follows:
Principal financial obligations arising from a mining licence
| Obligation | Foundations | Basis |
|---|---|---|
| State royalty | Mining Law, Art. 14 | The pithead price of the mineral extracted from the mine; for licences with an operating permit, the annual minimum amount is the licence fee plus 50 per cent |
| Licence fee | Mining Law | Separate from the state royalty; conditions on the validity of the licence and the fee |
| Rehabilitation fee | Mining Law, Art. 13 | Equal to the operating licence fee; earns interest in a special account |
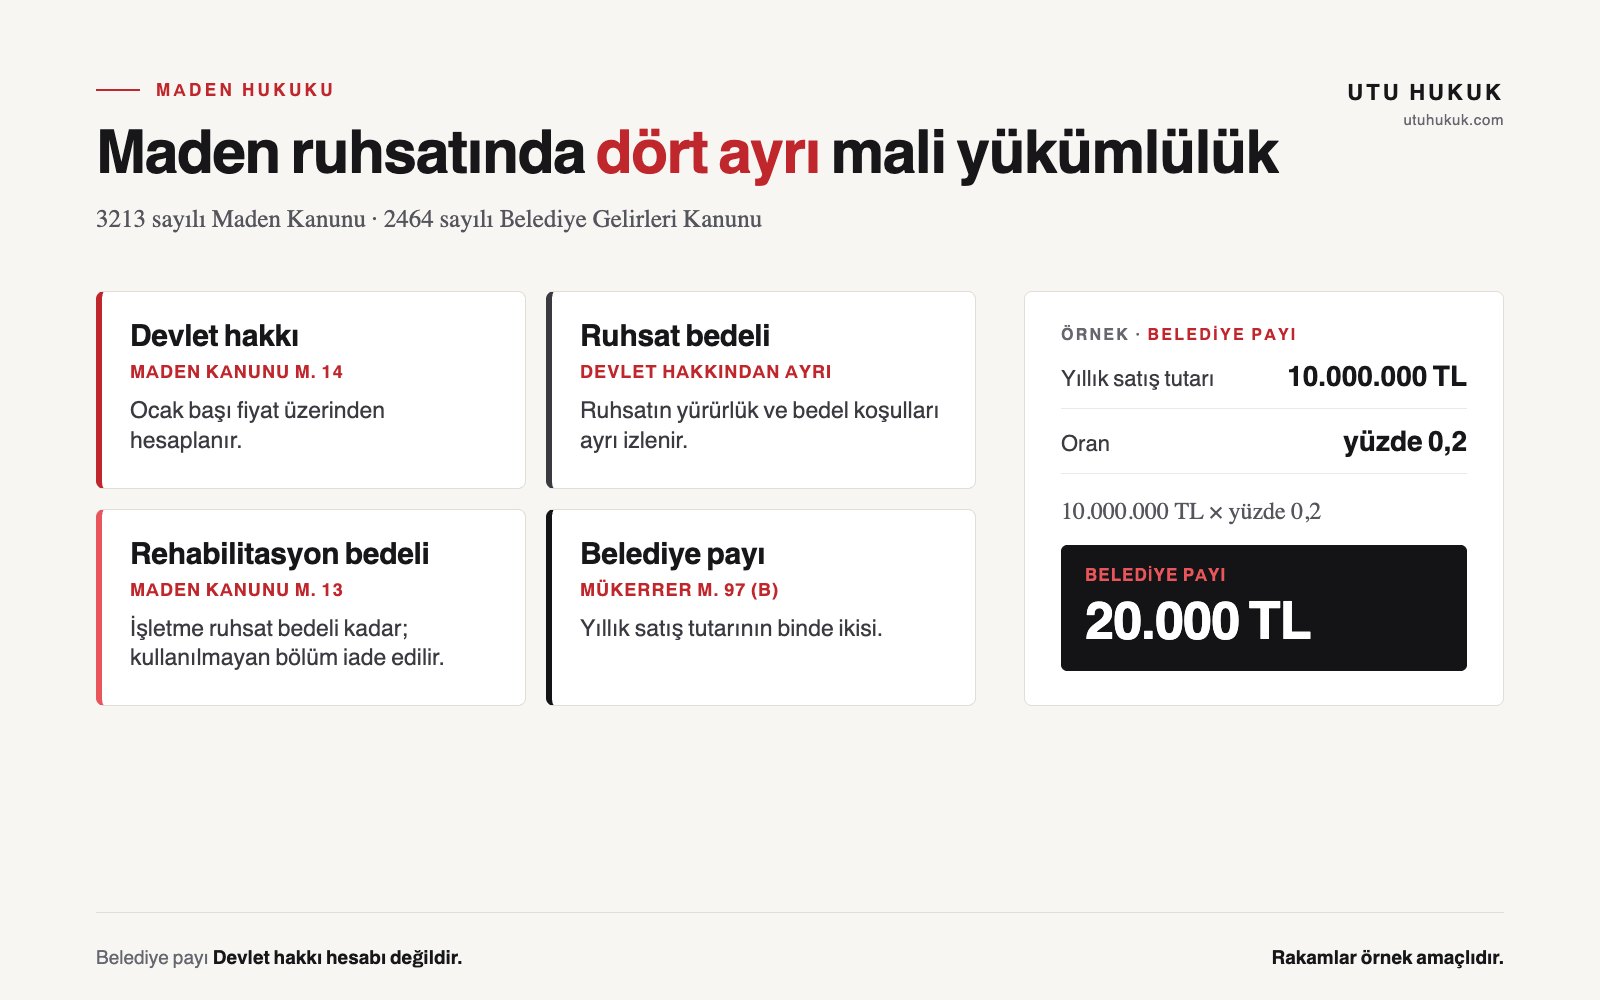
| Municipal share | Law No. 2464, Art. 97 bis (b) | 0.2 per cent (two per mille) of the annual sales amount |
The state royalty is a financial obligation calculated, under Article 14 of the Mining Law, on the pithead price of the mineral extracted from the mine. The licence holder’s declaration is subject to inspection. The use of the mineral as a raw material within the operation does not mean that the obligation automatically ceases. [1]
Where run-of-mine ore, in other words the mineral in the state in which it leaves the mine, is processed and sold, the sale price of the processed product and the pithead price are not regarded as the same. The necessary separation is made on the basis of the transport, beneficiation and processing costs permitted by the legislation. The calculation period, the connection with the activity and the documentation of each deductible expense must be examined separately. [1, 6]
The state royalty rate is not the same for all minerals. The mineral group, the type of mineral, the relevant price table and any increase or reduction decisions in force are important. Calculations for gold, silver and other relevant metals should not be made on the assumption of a fixed and unchanging percentage. The calculation is made on the basis of the legislation in force in the period to which the production relates.
Minimum amount
Law No. 7554 changed the minimum amount threshold in Article 14 to the licence fee plus 50 per cent and renewed the relevant price table. The rate and the minimum amount should be checked together. [5]
The licence fee is an obligation distinct from the state royalty. The production-related calculation and the conditions on the validity of the licence and the fee should be monitored separately. Rehabilitation, for its part, covers the works aimed at making the area affected by the activity safe and environmentally compatible.
The 2025 amendment regulated the rehabilitation fee separately in Article 13. The fee is equal to the operating licence fee; it earns interest in a special account and is used for rehabilitation. The unused portion is refunded to a licence holder that no longer has any obligation. Under Provisional Article 46, the previous provisions continued to apply until 1 January 2026 in calculating the licence fee and the environmental compliance fee (the former equivalent of the rehabilitation fee) for licences in force at that time; from that date onwards, the current provisions are applied. [5]
The distribution of the state royalty to the relevant public accounts and the collection of a separate municipal share from the licence holder are not the same matter. There are different provisions for the distribution of the state royalty depending on whether the province is a metropolitan one. An explanation providing for payment only to the special provincial administration for all provinces therefore does not fully reflect the current system. [1, 7]
Under sub-paragraph (b) of Article 97 bis of Municipal Revenues Law No. 2464, mining operations active within municipal boundaries and adjacent areas set aside a municipal share at the rate of 0.2 per cent, that is two per mille, of their annual sales amount. This obligation is separate from the state royalty. [8]
For example, if the annual sales amount on which the municipal share is based is determined as TRY 10,000,000, the share at 0.2 per cent is TRY 20,000. This example is not a state royalty calculation; it is based on the assumption that the sales base and the relevant municipality have been correctly determined in accordance with the specific statutory conditions.
Mineral exploration carries the risk that no economically operable reserve will be found. However, it cannot be said that all drilling, well, gallery, survey and other exploration expenditure will in every case be expensed directly and deducted from the tax base. The nature of the expenditure, whether it creates an asset or a right, the relevant tax period and the accounting rules to be applied must be examined separately.
Period expense, capitalisation and depreciation are different treatments. Article 316 of the Tax Procedure Law on depreciation of mines and the relevant income or corporate tax provisions are assessed together. A negative exploration result should not in itself be accepted as a reason for expensing every expenditure in the same period. A refund of licence and tender fees is also different from an expense deduction from the tax base. [9]
For licence holders, investors and heirs, the following points help the process proceed smoothly:
In mining investment, knowing the limits of the licence and the continuing obligations is as important as holding the licence. The legal nature of the mineral, the capacity of the right holder, the registry entries, land and production permits and financial obligations should be checked together. In particular, in transfer, inheritance and enforcement transactions, one should not be content with the general rules of private law; the special procedures of the Mining Law and the current regulations should be taken as the basis.
Kamu idarelerinin alım, satım ve kiralama ihalelerinde hangi kanunun uygulanacağını Devlet İhale Kanunu ile Kamu İhale Kanunu farkı in our article.
Related legislation: Mining Law No. 3213 (mevzuat.gov.tr)
Land ownership alone is not sufficient. The licences and permits required according to the nature of the resource must be obtained; land ownership and mining rights must be distinguished from one another.
The relationship between application and tender varies according to the mineral group. An initial application does not guarantee a definitive licence right for every site. Eligibility to hold mining rights does not mean that all the conditions required in the licence application have been met. Financial adequacy, project, technical documents, fee and security requirements may also arise at the relevant stage.
It does not grant an unlimited right to produce. Special provisions on samples and mandatory production during exploration are reserved. For commercial production, the operating licence, the operating permit and other relevant conditions are assessed.
Mining rights are granted in the name of a single natural or legal person and cannot be divided into shares. The situation is different where a company established by the partners holds the licence; in that case the right is held in the company’s name.
In the transfer of exploration and operating licences, the statutory transfer fee, the approval of the competent authority and the mining registry formalities are important. Article 5 of the Law provides that, before the transfer, a transfer fee equal to twice the licence fee applicable on the date of transfer is collected and that the transfer takes place with the approval of the Ministry. A transfer agreement between the parties does not replace the administrative approval and registry requirements.
The rights and obligations pass by inheritance. However, the principle of indivisibility and the eligibility, application period and registry requirements must be met. Where there is no pending action, a transfer by inheritance not completed within six months results in the cancellation of the licence.
No. The state royalty is a financial obligation. The ownership permissions and other legal bases required for access to and use of the land must be obtained separately.
Under subparagraph (b) of Article 97 bis of the Municipal Revenues Law No. 2464, mining operations operating within municipal boundaries and adjacent areas set aside a municipal share at the rate of 0.2 per cent, that is, two per thousand, of their annual sales. This obligation is separate from the state royalty.
Consultation request
As UTU Hukuk Danışmanlık, we provide legal and advisory services in the fields of tax and administrative law.
Fill in the form and we will call you. You can also contact us directly:
